


Blockchain is set to become one of the most disruptive innovations of the 21st Century. Initially known as the driving force behind the growth of cryptocurrencies like Bitcoin, the use cases of blockchain technology is growing at a rapid rate. The distributed ledger that powers blockchain can come with widespread benefits for small businesses, and carries the potential to revolutionize the payroll process.
If your business hasn’t yet encountered blockchain technology, the chances are it will in the coming years. The industry is growing exponentially thanks to the immutable nature of blockchain, which makes the act of tampering with the information it stores virtually impossible.
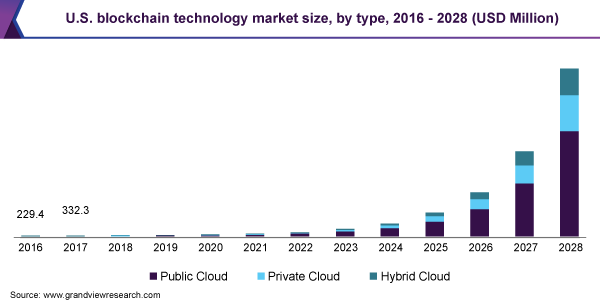
(Image: Grand View Research)
As the data above shows, the US blockchain technology market is expected to expand at a rapid rate – particularly in the second half of the decade, with public cloud applications set to take up a dominant role across the industry.
But what exactly is blockchain? And how can it improve payroll structures across businesses of all sizes? Let’s take a deeper look at one of the most exciting technological developments of recent times:
What is a Blockchain?
Blockchains exist as immutable distributed ledgers that are built on transactional data – which can be used to record the transfer of any asset of value. The assets that blockchains can store records of can be physical, like real estate or virtual, like cryptocurrencies.
Blockchain can also be used to verify the identity of individuals through an immutable record of their employment history, demographics, physical location, tax records and much more insight.
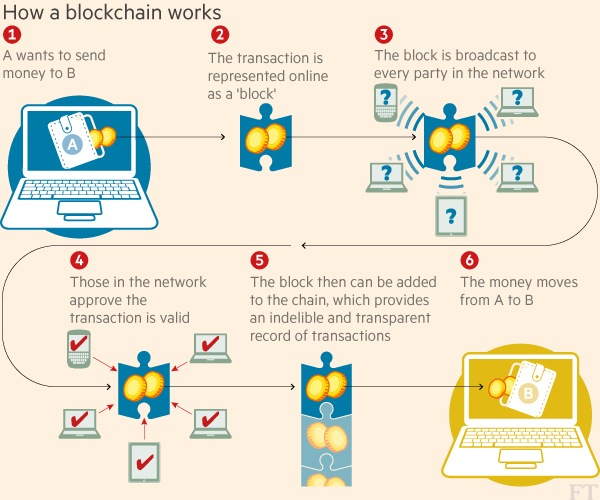
(Image: World Economic Forum)
The technology can be used for internal and external data transfer among both businesses and individuals alike. While business leaders are still learning about the potential upsides of blockchain, other enterprises are already working to incorporate digital ledgers into their daily practices.
As businesses process many different types of transactions on a daily basis – both internally and externally – blockchain possesses the power to improve the speeds of transactions, uphold a greater level of trust, and deliver comprehensive transparency.
How Blockchain can Change Payroll
Because blockchain’s immutable nature brings greater levels of trust, it’s possible to send money across borders without the need for middlemen, making the process of paying remote workers faster and more cost-effective – all with less chance of errors being made along the way.
Fewer errors and faster payments help to ensure that HR departments can avoid losing time and productivity on payment disputes between companies and their employees. As we transition towards the post-pandemic age of remote work, businesses with international employees can find blockchain payroll structures particularly beneficial.
As far as blockchain applications and payroll go, one of the first things that comes out is not only faster cross-border payments but less expensive and less error-prone cross-border payments, explained Tashina Charagi, vice president of ADP, one of the world’s largest payroll software companies.
Although blockchain payroll applications are still in their infancy, we can already see a healthy array of options available to businesses on the market, including firms like Papaya Global, Deel and Bitwage, all of which come packed with functions that can improve the quality of business payroll systems – particularly for companies that welcome remote employees.
Greater Payment Clarity
When it comes to blockchain, employers and employees alike have the ability to keep track of what’s been paid and trace payments back all the way to the first paycheck issued. If any disputes occur, or an employee believes they’ve received the incorrect pay, the ledger is easy to consult and adjustments can be made accordingly in an efficient manner.
This extra clarity can also be great for studying payroll-related transactions. For example, employers will be able to see how much tax they’re paying to the government on the chain – which could help to highlight any emerging issues in terms of the rates that they’re paying. Employees can likewise consult the block to better understand their direct pay and the deductions that are being taken from their wages.
Furthermore, because blockchain ledgers are publicly accessible, it’s also possible for governments to visualize fully what’s been paid to them in taxes whilst gaining insights into what’s owed. This can be highly beneficial to businesses in preventing instances of fraud, both from employers and their independent contractors. It also has the potential to remove the necessity of IRS auditing – saving plenty of time and hassle.
The Future is Now
Blockchain has long been identified as the technology that could bring a revolution in how businesses handle payroll, and the pandemic may have begun accelerating this change at a faster pace than most had imagined.
With economic stimulus required around the world, the integral role that blockchain is set to play in the age of the new normal is sure to drive further interest in the technology across a range of industries.
Further to this, the capability of blockchain to reduce the roles of the payroll middlemen carries greater appeal than ever before – as the growing financial needs of employees are met with reduced capacities of banks. The role that blockchain will play in the future of finance seems clear, though we may see its emergence occur at a faster pace than first thought.Â
